How to Consolidate Debt with a High Debt-to-Income Ratio?




At a Glance
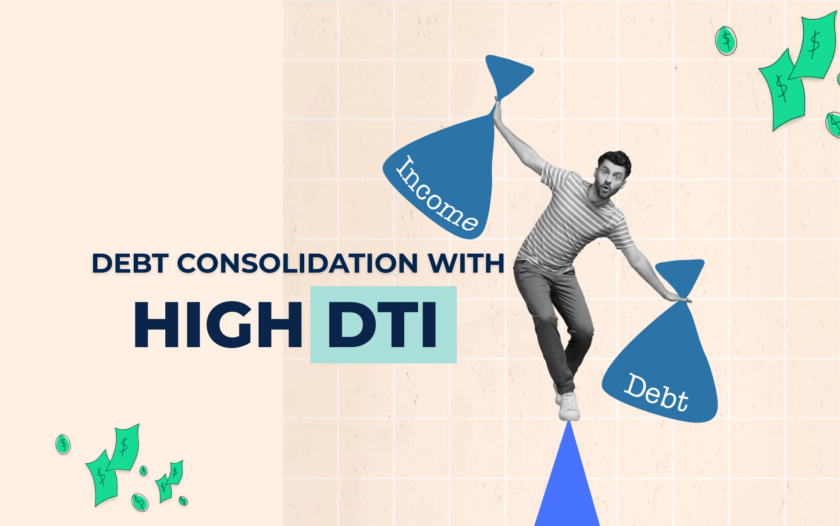
While a debt consolidation loan allows you to pay off your existing debt by combining it into a single loan, lenders typically like to see a healthy debt-to-income or DTI ratio before lending to you. For those with higher debt levels this can seem like a troubling hurdle, but by learning to calculate your own DTI and the loan options available to you, you can improve your debt today.
To learn more about each, click below:
What is a high debt-to-income ratio?
The value considered to be a high debt-to-income ratio can fluctuate depending on the type of loan you seek, but generally a value above 43% is high. For some loans, such as consolidation loans, the max DTI lenders like to see may be as high as 50%, but it’s important to research every individual lender. As mentioned, these values can vary, but use the following as a rule-of-thumb:
- 0%-36%: This is a strong debt-to-income ratio that demonstrates you likely know how to manage your money effectively.
- 37%-43%: This is the middle-ground for a debt-to-income ratio where it’s still a strong chance that a person is managing their debt well, but more questions may be required.
- 44%-50%: This is where things begin to get high-risk and when lenders start to seriously question whether or not to approve an application.
- 50% and above: Those with a debt-to-income ratio in this category can essentially kiss their hopes of approval goodbye without additional information to support their case.
However, to answer the question of, “what is a high debt ratio?” properly you will need to calculate your own. By determining this value, you can also determine what debt consolidation strategies you may be eligible for.
How to calculate debt-to-income ratio?
The simple formula for calculating your debt-to-income ratio is to take all your existing monthly debt payments and divide the value by your monthly pre-tax income. Then, multiply the result by 100 to get your percentage. This may seem straightforward, but identifying all your debt payments can be challenging. Here is an example that may help you to visualize the process. Say you have the following monthly debt payments:
- Student loan payments: $300
- Credit card minimum payments: $200
- Auto loan payment: $400
This equates to a numerator of $900 in debt for the month. On top of this, say your pre-tax earnings are $3,000 for the month. When you divide these two values and multiply by 100, you get a debt-to-income ratio of 30%.
In addition to all of the above, there are other common expenses which fall into your debt-to-income ratio which are important to know about. The most notable of these include: monthly rent or mortgage payment, personal loan payments, child support or spousal support payments, and other types of loan payments.
Expert tip from Thomas Brock: Your debt-to-income ratio is important to potential lenders, because it indicates the proportion of your current income that goes toward servicing existing debts. The higher the ratio, the less financial flexibility you have and the greater the credit risk you pose to new lenders.
How high DTI can impact debt consolidation?
As mentioned, having a high DTI means that lenders will naturally consider you to be a higher risk than others who are applying for loans or credit cards. This means that some debt consolidation solutions such as balance transfer cards or personal loans, discussed further down, may not be viable strategies. The interest rate offered for debt consolidation strategies may also be higher than normal due to having a high DTI which will make the entire process of debt consolidation lengthier, as it will likely take longer to pay off the debt.
Options for debt consolidation with high DTI
Debt consolidation with high debt to income ratio can be a challenge, but there are various strategies and loan types to accomplish this goal. Specific high debt to income ratio loans, such as personal loans for high debt to income ratio, are designed to help those who may have a DTI above 40%.
1. Secured personal loan
While lenders may not be willing to provide you with an unsecured personal loan when you have a high DTI ratio, they may offer you a secured personal loan. The primary difference between these two types is that a secured loan requires a borrower to put down collateral. This collateral can be anything from your car to other assets you may own. The reason lenders are more willing to offer a secured personal loan to somebody with a high DTI is that in the event of non-payment by the borrower, the lender can still collect on something of value. Read more on the differences between secured and unsecured loans here.
Related: Secured vs Unsecured Personal Loans
2. Home equity loan
A home equity loan is a secured type of loan in which a borrower receives funds in exchange for offering equity in their home as collateral. As discussed earlier, this allows the lender to perceive the borrower as having less risk, so they are more willing to provide the loan. The amount of the loan is determined by the value of the property as determined by an appraiser.
Related: Best Home Equity Loans
3. Loan with a co-signer
Lenders have certain requirements you must meet in order to get approved for a loan, such as a minimum credit score or income requirements. If you don’t have these, a cosigner can help the lender feel more comfortable giving you the loan. Because someone else is pledging to repay the loan if you don’t, the loan is considered less risky.
Personal Loans with a Co-Signer
 Use the filters below to refine your search

 8 results that match your needs




 6 min