Planning to Borrow from your 401(k)? Here’s What to Know




At a Glance
Carrying too much debt is a problem that can affect you in several other areas of life. At first glance, using funds from your 401(k) plan to pay off that debt may seem like a good idea, particularly if you have high-interest credit cards. It’s your money. Why not use it? That’s the question we’ll attempt to answer for you today. Here’s what we’ll cover:
What is a 401(k) loan?
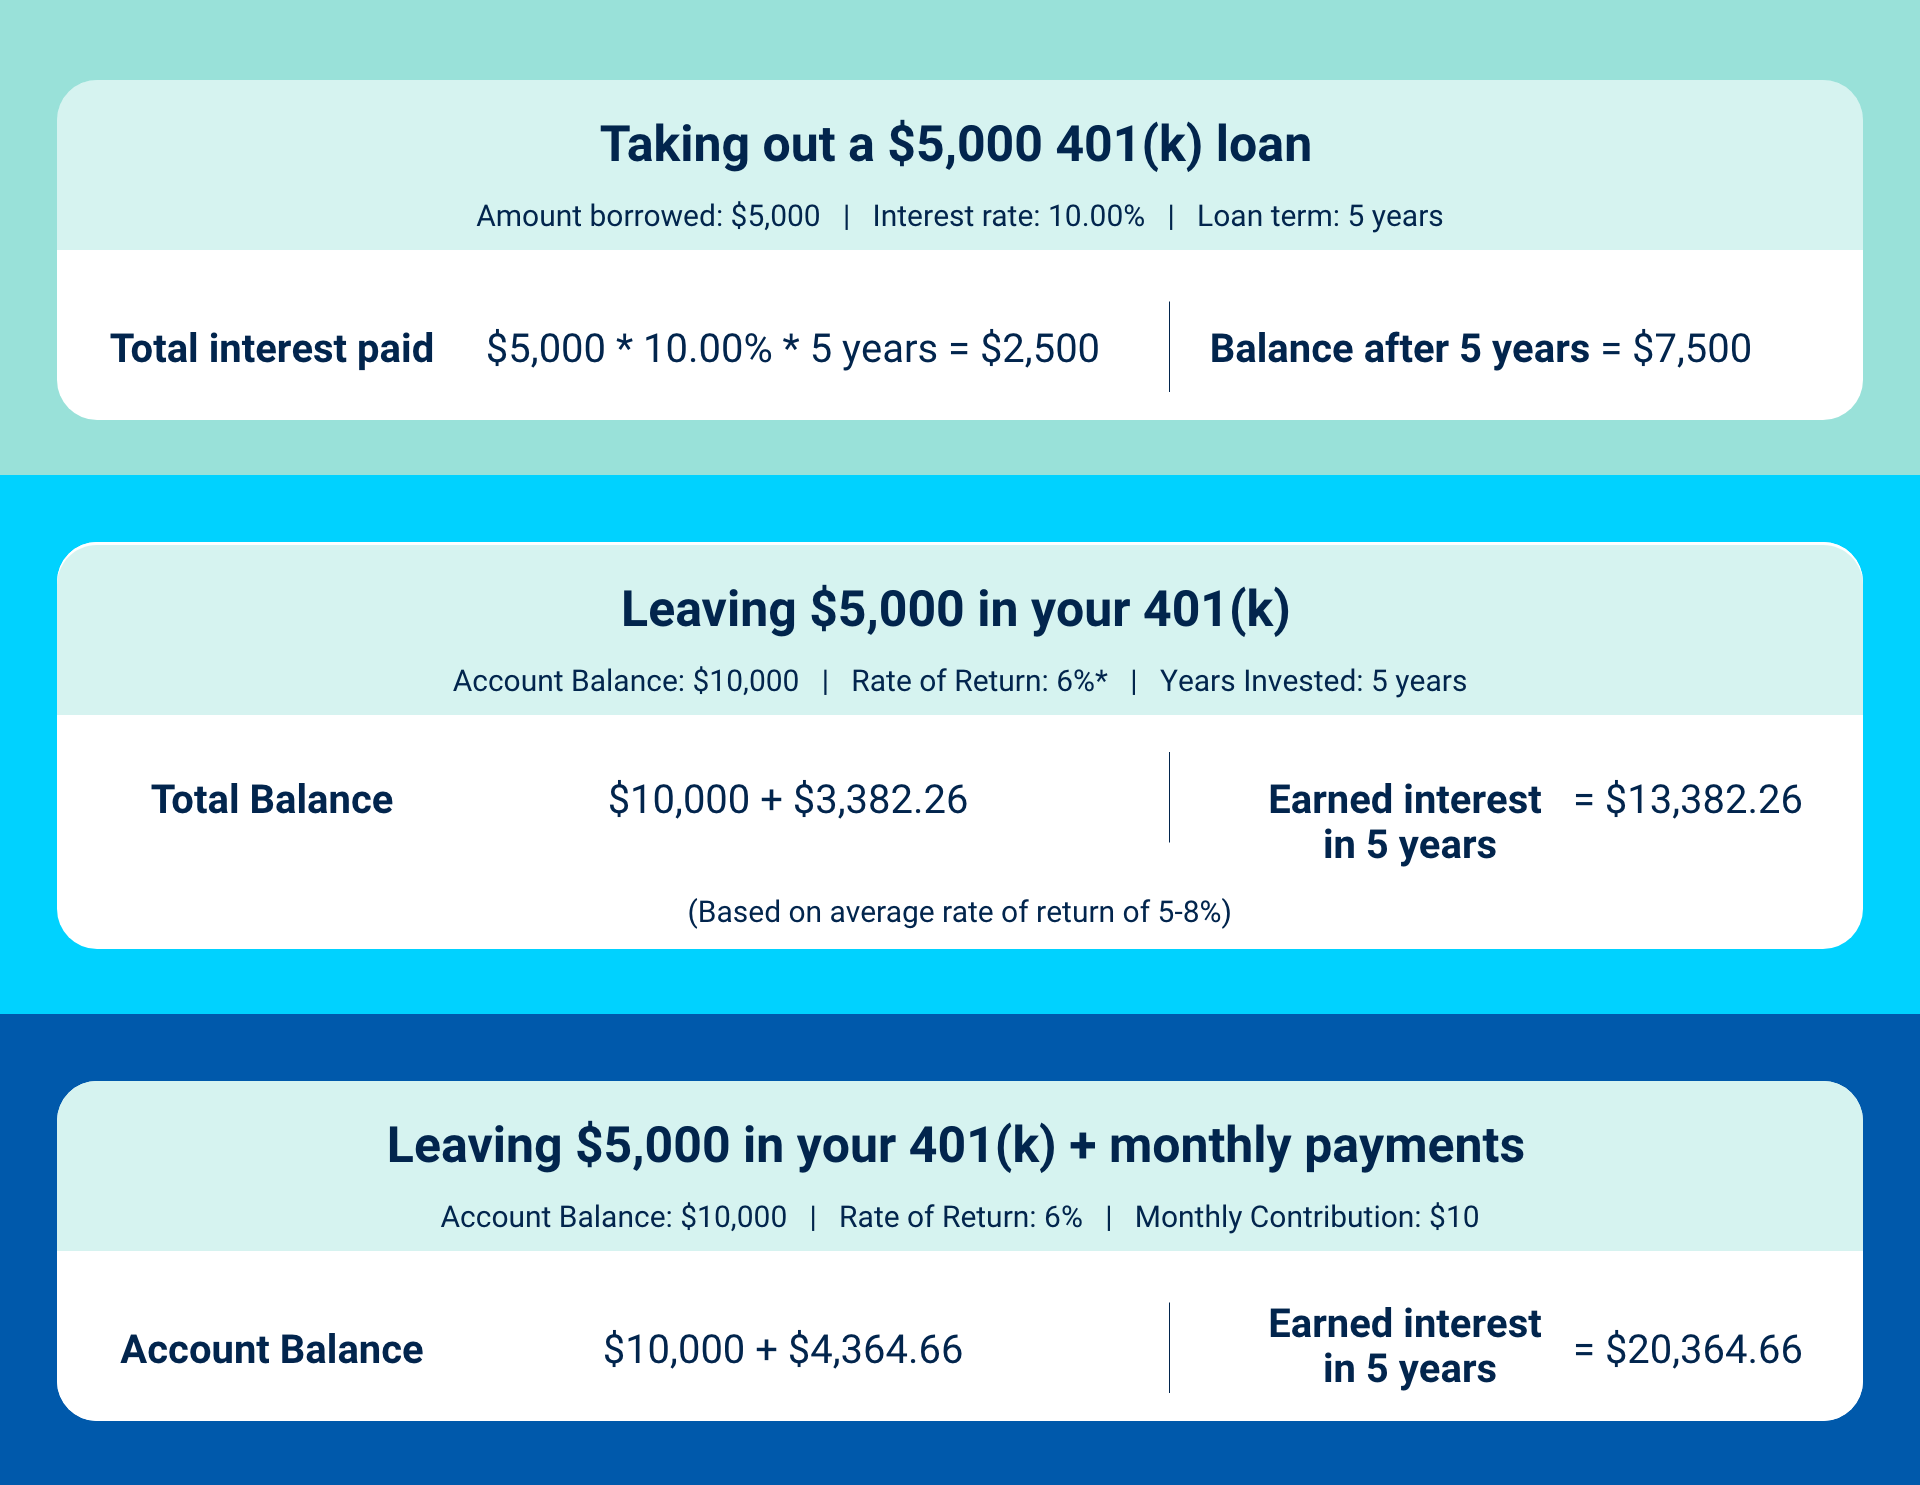
A 401(k) loan allows you to borrow money from your retirement savings and pay it back to yourself over time, plus interest. You can typically borrow up to 50% of your balance for up to five years, for a maximum of $50,000.
The interest rate is typically the current prime rate plus 1%. Once you sign the paperwork, you’ll have access to the funds within a few days. Then, the loan payments and the interest get paid back into your account.
Not every plan lets you do this, and how much you’re able to borrow, how often, and repayment terms are dependent on what your employer’s plan allows. The plan may also have rules on a maximum number of loans you may have outstanding on your plan. Note that if you leave your current job, you may have to repay the loan in full very quickly. Or, if you default, you’ll owe both taxes and a penalty if you’re under age 59 ½-years-old.
Should you use a 401(k) loan to pay off debt?
There are a number of reasons you may consider borrowing from your 401(k), including to pay off debt. If you have high-interest debt, such as credit card debt, consolidating it with a 401(k) loan can lower your overall interest rate and simplify your payments:
1. Lower interest rates: The interest rate on a 401(k) loan is typically lower than that of credit cards or other high-interest debt, potentially saving you money on interest payments.
2. No credit check: Since you’re borrowing from your own retirement savings, there’s no need for a credit check, making it easier to qualify for a 401(k) loan than other types of loans.
3. Interest goes back to you: The interest you pay on the loan goes back into your own 401(k) account, essentially making it a self-borrowing option.
4. Quick access to funds: Unlike traditional loans, which may take time to process, you can usually get a 401(k) loan quickly, providing immediate access to funds.
In addition to paying off debt, some other scenarios when it may make sense to take out a 401(k) loan include:
1. Emergency expenses: If you’re facing a financial emergency and have no other means to cover the costs, a 401(k) loan can provide quick access to funds without penalties or taxes (as long as you repay it on time).
2. Home purchase: Some 401(k) plans allow you to use the loan for a down payment on a home, which can help you avoid costly private mortgage insurance (PMI).
3. Cash flow needs: If you need short-term cash flow for a specific purpose, such as starting a business, a 401(k) loan can provide the necessary funds.
It’s best practice to first explore other options for debt repayment, but if those are ruled out, a 401(k) loan might be an acceptable choice.
Alternatives to a 401(k) loan
When considering your financial situation and needs, a 401(k) loan may be an option. However, there are other alternatives that should be considered as well:
Negotiate your interest rate
Before taking out a 401(k) loan, consider negotiating your interest rate on your current debt. This can be a helpful strategy for reducing how much you owe and making your debt more manageable. Here are some steps you can take to negotiate a lower interest rate:
1. Understand your current rates: Know the interest rates you’re currently paying on your debts, such as credit cards, loans, and lines of credit.
2. Research competitive rates: Research current interest rates for similar financial products to understand the market rates and use them as a benchmark for negotiation.
3. Contact your creditors: Call your creditors directly and explain that you’re interested in lowering your interest rate. Be polite and persistent. Mention your good payment history and inquire about any available promotional rates or programs.
If negotiating on your own is challenging, consider seeking help from a credit counseling agency or a debt settlement company. They can negotiate on your behalf and help you develop a plan to manage your debt.
Personal loans
Personal loans are a type of loan you can borrow from a bank, credit union, or online lender. Loan funds can be used for just about any reason, making them a good option for well-qualified borrowers who need financing. Terms and interest rates vary based on lender, your credit score and history, and other factors, but borrowers with good to excellent credit typically qualify for lower interest rates.
These loans are usually unsecured, meaning they don’t have to be backed by collateral, and have fixed terms and rates, so you can quickly and easily calculate your monthly payments, how much the loan will cost over time, and when you’ll have it paid off.
Give yourself options
 Use the filters below to refine your search

 10 results that match your needs




 Expert tip from Thomas
 6 min